- 0
- 651 words
Counting Tenants, Reading Signals: The Retail Geography of Chinese Brand Expansion in Singapore
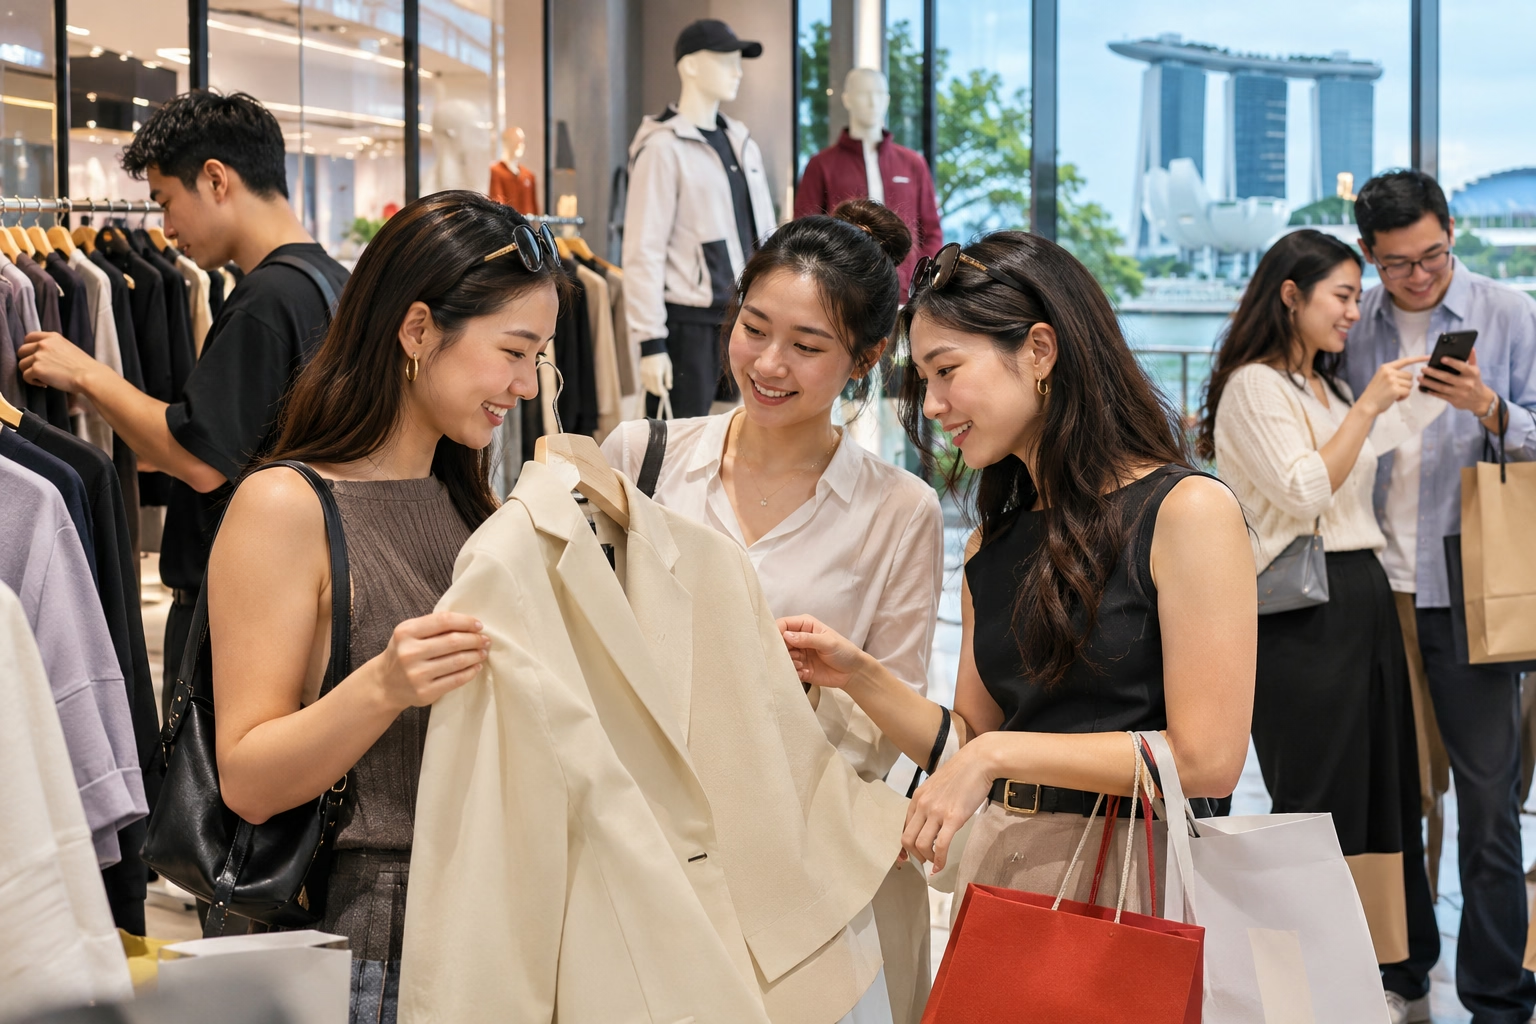
The most concrete way to understand the Chinese fashion wave in Singapore is not through press releases or runway shows, but through mall tenant lists. A comparative survey of 26 Singapore shopping malls—including ION Orchard, NEX, AMK Hub, Tampines Mall, Paragon, Northpoint City, JEM and Jurong Point—found that Chinese brand tenants rose from 122 in 2023 (2.46% of all tenants) to 254 in 2026 (4.97%), an increase of 132 brands. In the same period, the absolute number of Singaporean brand tenants also grew, from 3,260 to 3,366, with their share of total tenancy essentially unchanged at around 65.9%. The data tells a more nuanced story than the anecdotal “malls feel Chinese now” narrative: Chinese brands are expanding into a growing retail pie, not cannibalising local representation at the aggregate level.
Fashion’s Share of the Influx
The 132-brand increase spans food and beverage, beauty, toys and lifestyle, but fashion has been a visible and strategically important component. The past two years have seen a record number of Chinese fashion and beauty openings, including C-beauty players Judydoll and Joocyee, sports brand Anta, luxury eyewear brand Bolon, sun-protection apparel brand Oh Sunny and footwear label Vivaia. In womenswear specifically, Edition, Mo&Co, Goelia, Marisfrolg and Aimer have all established brick-and-mortar presence. These are not identical business models. Some are single-brand monobrand stores; others are wholesale or franchise arrangements. But collectively they represent a shift from cross-border e-commerce and daigou-led discovery to formal, lease-holding retail presence—a shift that changes the brand-consumer relationship from transactional to experiential.
Why the Percentage Still Matters
At just under 5% of total tenants, Chinese brands remain a minority presence in Singapore malls. That percentage matters because it defuses the zero-sum framing that sometimes dominates public discussion. The survey data shows that local brands are not disappearing; they are growing in absolute terms. The perception of saturation is driven partly by visibility: Chinese brands often occupy high-traffic locations, invest heavily in store design and generate social media buzz that amplifies their apparent presence beyond their numerical share. For fashion brands evaluating Singapore, the lesson is that the market can absorb new entrants—but the bar for visibility is higher than raw tenancy numbers suggest. A brand that opens quietly in a secondary mall without a differentiated product or a strong content strategy is unlikely to register in the consumer consciousness the way the early movers have.
The Landlord Perspective
Singapore landlords have their own calculus. In a retail environment where footfall patterns have shifted and e-commerce continues to pressure physical stores, Chinese brands offer something landlords value: novelty, speed and a willingness to invest in fit-outs. Ms Elaine Tan, a senior lecturer at Republic Polytechnic’s School of Business, describes the influx as a “deliberate, aggressive market entry strategy” by brands facing saturation and intense competition at home, with Singapore serving as a “high-visibility regional hub” with predictable consumer behaviour and strong mall infrastructure. That landlord openness is a window, not a permanent condition. As more Chinese brands enter, the differentiation pressure will move from “are you Chinese?” to “what specifically do you offer that the mall’s existing mix does not?”
The Next Data Point to Watch
The 2026 tenancy data is a snapshot of a market in motion. The more revealing metric will be store-level productivity and lease renewal rates over the next 24 months. A brand can enter a mall with an attractive fit-out and a launch campaign; sustaining the lease requires sell-through, repeat footfall and a product assortment that earns a second visit without novelty-driven discounting. The Chinese fashion brands most likely to endure in Singapore are those treating the city-state not as a trophy market for regional headquarters bragging rights, but as a rigorous consumer laboratory where climate adaptation, price-tier positioning and service culture are tested at full resolution. The 132-brand increase is the opening chapter; the renewal cycle will write the verdict.
Author

Clara@gmail.com
Related Posts
231,000 Tonnes, 3% Recycled: The Hard Numbers Reshaping Singapore’s Reworked Fashion Industry
- 0
- 499 words
The Gap Between Discard and Recovery Singapore’s reworked fashion scene is often framed through individual brand stories — a sold-out sari launch,...
Read out all
Why Sari Upcycling Is Becoming Singapore’s Most Culturally Specific Circular Fashion Story
- 0
- 464 words
The Cultural Logic of Reuse Upcycled fashion in Singapore is often framed through the language of waste reduction: diverting textiles from incineration,...
Read out all
How Singapore’s Homegrown Fashion Labels Rebuilt Their Business Around Livestreaming
- 0
- 514 words
From Side Channel to Core Business Model For a growing cohort of Singaporean fashion brands, livestreaming is no longer a supplementary marketing...
Read out all
Localization as Strategy: How Singapore Fashion Brands Speak Asia’s Many Languages
- 0
- 604 words
The End of One-Size-Fits-All Expansion Singapore fashion brands expanding across Asia are discovering that regional success requires more than translated marketing. Love,...
Read out all
The Comfort Revolution: How Singaporean Footwear Brands Are Redefining Support, Health, and Everyday Wear
- 0
- 658 words
From Pain Point to Product Innovation: The Sunnystep Story Sometimes the most disruptive innovations emerge from the most personal struggles. Mao Ting,...
Read out all
Gen Z vs. Gen X—The Generational Battle Over Singapore’s Office Dress Code
- 0
- 576 words
Two Generations, Two Definitions of Professionalism Walk into any Singapore office in 2026, and you may witness a quiet cultural collision. A...
Read out all